The Casebook · The tally sticks
The tally sticks
Every case in the Casebook, counted: 47 decided disputes from the Tax Appeals Tribunal and the courts, by what they were about, who won, how long they took and how much was at stake.
- decided disputes in the book
- 47
- decided disputes in the book
- in this selection went for the taxpayer; not a win rate
- 18 of 47
- in this selection went for the taxpayer; not a win rate
- in this selection upheld the liability, in full or to recompute
- 25 of 47
- in this selection upheld the liability, in full or to recompute
- median, from the disputed period to the decision
- 7 years
- median, from the disputed period to the decision
The oldest tax record there is
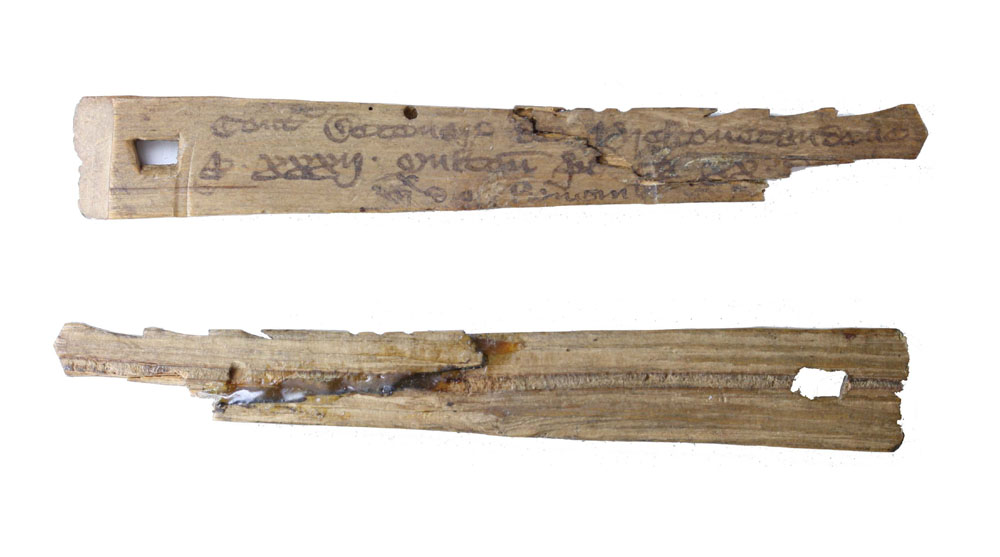
For about seven centuries England's Exchequer recorded tax on split sticks: a bigger sum cut a wider notch, and each side kept a half, so neither could cheat. The practice ended in 1826. In 1834 the old sticks were burned in the furnaces of Parliament, and the fire destroyed most of the building. So here is the count, cut the same way.
- Cross-border and related parties13 rulings · median 8 years · UGX 89.4bn
- Deadlines and procedure10 rulings · median 7 years · UGX 42.6bn
- Evidence, estimates and reconciliations9 rulings · median 8 years · UGX 14.4bn
- Exemptions, remissions and zero-rating9 rulings · median 8 years · UGX 54.2bn
- What kind of income or supply7 rulings · median 6 years · UGX 31.7bn
- Collection and enforcement7 rulings · median 6.5 years · UGX 59.8bn
- Deductions, losses and interest6 rulings · median 6 years · UGX 11.1bn
- The Revenue Authority's past positions5 rulings · median 10 years · UGX 5.3bn
- Customs classification4 rulings · median 8 years · UGX 5.7bn
- The 30% deposit and the route of appeal3 rulings · median 3 years · UGX 33.7bn
- Informer rewards2 rulings · median 10 years · UGX 4.2bn
A wider, deeper notch is a bigger sum (log scale) One thin cut: no sum reportedTTaxpayerUURAPSplitSSent back
A ruling is notched on every stick it belongs to, so the sticks add up to more than 47. This is a selected collection, and a tally of it is not a win rate. The sticks are drawn; the photograph above is a real one.
How long it took
The same count as tables
By what the dispute was about
| Category | Cases, by who they went for | For the taxpayer | Median years | At stake |
|---|---|---|---|---|
| Cross-border and related partiesTransfer pricing, imported services, withholding on non-residents | 13 | 2 of 13 | 8 (12) | UGX 89.4bn (10) |
| Deadlines and procedureObjection and appeal windows, ADR, time limits on assessment | 10 | 3 of 10 | 7 (6) | UGX 42.6bn (9) |
| Evidence, estimates and reconciliationsAssessments built on variances, estimates or missing records | 9 | 4 of 9 | 8 (8) | UGX 14.4bn (7) |
| Exemptions, remissions and zero-ratingWhether a relief applies, and to which part | 9 | 5 of 9 | 8 (9) | UGX 54.2bn (8) |
| What kind of income or supplyRent or business income, payment or not, benefit or not | 7 | 2 of 7 | 6 (7) | UGX 31.7bn (7) |
| Collection and enforcementAgency notices, sealing, distress, recovery from related companies | 7 | 3 of 7 | 6.5 (4) | UGX 59.8bn (6) |
| Deductions, losses and interestWhat can be deducted, capped or carried forward | 6 | 1 of 6 | 6 (6) | UGX 11.1bn (5) |
| The Revenue Authority's past positionsWhether earlier advice or practice binds it (legitimate expectation) | 5 | 3 of 5 | 10 (4) | UGX 5.3bn (4) |
| Customs classificationWhich tariff heading, and so which duty rate | 4 | 2 of 4 | 8 (3) | UGX 5.7bn (4) |
| The 30% deposit and the route of appealPaying to be heard, and which court hears what | 3 | 2 of 3 | 3 (2) | UGX 33.7bn (1) |
| Informer rewardsWho gets paid, and at which rate | 2 | 1 of 2 | 10 (1) | UGX 4.2bn (2) |
By tax
| Category | Cases, by who they went for | For the taxpayer | Median years | At stake |
|---|---|---|---|---|
| Income tax | 19 | 6 of 19 | 6 (16) | UGX 31.9bn (15) |
| VAT | 15 | 8 of 15 | 8 (12) | UGX 90.4bn (14) |
| Customs | 7 | 3 of 7 | 10 (6) | UGX 6.3bn (6) |
| Procedure | 5 | 3 of 5 | 3 (2) | UGX 55.5bn (3) |
| Withholding tax | 3 | 0 of 3 | 10 (3) | UGX 26.2bn (3) |
| Excise | 2 | 0 of 2 | 3.5 (2) | UGX 18.5bn (1) |
| Informer reward | 2 | 1 of 2 | 10 (1) | UGX 4.2bn (2) |
| PAYE | 1 | 0 of 1 | 7 (1) | UGX 1.8bn (1) |
| Stamp duty | 1 | 0 of 1 | 11 (1) | UGX 0.1bn (1) |
- Most cases in the book are about cross-border and related parties: 13 of 47.
- Among categories with five or more cases in this selection, the largest share went for the taxpayer on the Revenue Authority's past positions (3 of 5) and the smallest on cross-border and related parties (2 of 13).
- Cases about the Revenue Authority's past positions took longest: a median of 10 years from the disputed period to the decision.
These are patterns in this collection, not in all disputes; see the limits below.
The caseload behind the cases
- Cases pending at the Tribunal rose from 169 in 2022/23 to 476 in 2024/25, with about UGX 1.5 trillion tied up in tax disputes and an average of about ten months to resolve a case, according to the Auditor General's 2025 report and the Tribunal's chair, as reported by Sanyu FM (17 February 2026).
- The Revenue Authority historically wins about 93% of its Tribunal disputes, according to the Daily Monitor (2 September 2026).
What this map can and cannot tell you
- It counts the 47 cases in this book, not every dispute. Thirty come from the Revenue Authority's own Case Digest, which covers one half-year; the rest were reported by advisers or the press, who write up the unusual and the large. Taxpayers win more often here (38%) than the Authority's reported overall record would suggest, which is what that selection would produce.
- Categories are our classification of each case, and many cases belong to more than one.
- Time is measured from the first year of the disputed period, not from the assessment, so it includes the years before the audit; where that year is not reported the case is left out.
- Amounts are as reported and are not adjusted for inflation; some are the assessment, some the sum finally in dispute.
Sources for the sticks: Wikipedia, Tally stick; Science Museum Group, Exchequer tallies. Every case behind these numbers: the cause list. What they suggest should change: the brief.
Sources: the cases in the Casebook (47); Sanyu FM, ‘UGX 1.5 trillion locked in tax appeals’, 17 February 2026; Daily Monitor, ‘URA loses over Shs1 billion in Medisell tax dispute’, 2 September 2026.